

Greenlight: For Families
by Greenlight Financial Technology, Inc.
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
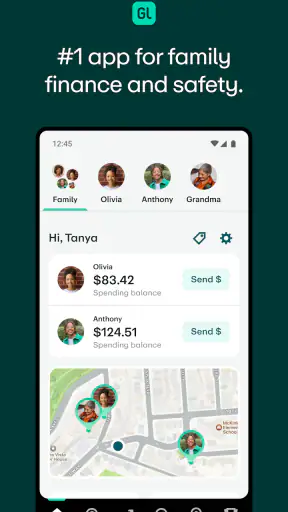
If you want to give a child a practical way to learn about spending without handing over a traditional bank card, Greenlight: For Families is worth a close look. I found its main appeal easy to understand: the child uses a debit card, while the parent manages the experience from an app. That arrangement makes everyday money decisions visible instead of leaving them as vague conversations about saving and responsibility.
This is a finance app rather than a general budgeting tool, and it is aimed at families who want a supervised starting point for children and teenagers. The developer is Greenlight Financial Technology, Inc., and the app is free to install. Its Everyone age rating makes the audience broad, although the real value depends on a parent being willing to take an active role rather than simply giving the app to a child and walking away.
What Greenlight feels like in everyday family use
The first thing I would set expectations about is the division of control. A child gets a spending instrument, but the parent remains the person organizing the financial experience through the app. That is different from giving a teenager cash, and it is also different from opening a standard banking app and expecting a young user to understand every decision alone.
In practice, the app works best when it becomes part of a family routine. A parent can use it as the place to discuss spending, saving and the difference between a want and a need. The child gets a more concrete connection between a decision and its result. I would not treat it as a replacement for conversations about money; I would use it to make those conversations less abstract.
The app has been available since December 23, 2016, and its current version is 8.6.0. It has reached over a million installs, with an average rating of 4.7 from around 85 thousand ratings and roughly 11 thousand written reviews. Those figures suggest that it has found a substantial audience, but they do not remove the need to decide whether its parent-managed approach fits your household.
For a first-time user, the most useful mental model is this: you are not merely downloading a card companion for your child. You are setting up a small family system. The parent side needs attention, the child needs clear expectations, and both sides benefit when the rules are agreed before the first purchase happens.
Who is likely to appreciate it
I think Greenlight is particularly suitable for a parent whose child is beginning to make independent purchases but still needs boundaries. It can also suit families that want to move gradually from cash to card spending while keeping an adult involved. A teenager who regularly buys snacks, school supplies or small personal items may gain more from this structure than a child who rarely spends independently.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
It is less convincing for someone looking for a completely hands-off solution. If you want to give a young person unrestricted control, the parent-managed design may feel like too much supervision. It may also be the wrong choice if your family prefers physical cash, a simple allowance jar or an existing bank arrangement that already provides the controls you need.
What to prepare before installing
Before opening the app, I would decide what the card is meant to teach. Is the goal safer everyday spending, a regular allowance, saving toward a purchase, or simply giving a teenager a controlled first step? Without that decision, the app can become just another place to check transactions.
I would also agree on a few simple household rules. Decide which purchases are ordinary, which require a conversation, and how the child should respond if a transaction is declined or looks unfamiliar. This preparation matters because the technology can show what happened, but it cannot decide what a particular family considers responsible.
The app supports devices running operating system version 10 or later. That is an important practical check before setup, especially if the child will use an older phone. I would confirm that the parent’s device and the child’s device are both suitable before planning a first purchase around the service.
Getting from installation to the first useful result
I’d use the first setup session to settle one practical question before a child reaches for the card: what should they do if a purchase does not go as expected? Agree on a simple way to pause and ask for help, then keep the first outing low-pressure. That gives the family a workable starting point and makes it easier to build a routine around the app.
Start with the parent side, not the card
My advice is to begin with the adult account and take a few minutes to understand the management flow before involving the child. The parent is the person who needs to know where to review activity, how to organize the child’s spending experience and how to explain the rules. Rushing straight to handing over a card can create confusion later.
During setup, keep the conversation with your child straightforward. Explain that the card is for agreed spending, that the parent can manage it, and that checking activity is part of learning rather than a punishment. That wording makes a difference. A child who sees every review as surveillance may avoid asking questions, while a child who understands the purpose is more likely to learn from mistakes.
I would avoid trying to configure everything around a complicated system on the first day. Start with one child, one clear purpose and a small number of expectations. Once the family understands the rhythm of using the app, you can decide whether a more detailed routine is useful.
Make the first successful action deliberately small
The best first milestone is not a large purchase. It is a simple, planned transaction that the child understands before it happens. For example, you might agree that the child will use the card for a small school-day purchase, then review the activity together afterward. The point is to connect the physical purchase with what appears in the parent-managed app.
After that first transaction, ask three practical questions: What did you buy? Was it planned? What would you do differently next time? This turns a notification or transaction entry into a short lesson. I found that this kind of review is more useful than giving a long lecture about budgeting before the child has any real experience to discuss.
A second helpful exercise is to ask the child to predict the effect of a purchase before making it. If the purchase uses money intended for a particular goal, the child can think through that trade-off in advance. This is one of the less obvious strengths of a managed debit-card setup: the learning happens at the moment a decision is made, not only at the end of the month.
Use a repeatable weekly check-in
Once the first transaction goes smoothly, I would create a short weekly check-in rather than checking constantly. Look at recent activity, discuss anything unexpected and ask whether the current arrangement still matches the child’s needs. A predictable routine helps the app feel like a tool for independence instead of an emergency dashboard.
Keep the review focused. If the child made a sensible choice, say so. If a purchase was unnecessary, ask what led to it and what alternative might have worked. The goal is not to eliminate every imperfect decision. A supervised mistake can be more educational than a parent making every choice in advance.
Three practical habits that add more value
- Separate the learning goal from the spending amount. A small purchase can teach planning just as effectively as a larger one. Begin with an amount that makes mistakes manageable, then adjust only after the child understands the routine.
- Review activity with the child present. Instead of treating the parent app as a private control panel, use selected transactions as conversation starters. This builds transparency and reduces the chance that the child sees the card as mysterious or disconnected from the family rules.
- Test the family’s response to an unexpected transaction. Agree beforehand that the child should tell a parent immediately, rather than hiding the problem or repeatedly trying the card. Having a calm procedure is more useful than assuming every purchase will go perfectly.
Where first-time users may hesitate
The biggest adjustment is accepting that there are two experiences to manage: the child’s use of the card and the adult’s oversight through the app. A parent who expects a normal standalone debit card may find the arrangement more involved than anticipated. That extra involvement is the product’s purpose, but it can still feel like friction during the first few days.
Another possible sticking point is family communication. If one adult says a purchase is acceptable and another treats it as a problem, the child receives mixed signals and the app gets blamed for a rule that was never clear. I would settle those expectations before the card becomes part of daily life.
There is also a temptation to measure success by how little the child spends. I do not think that is the right test. A child who spends carefully on an agreed need and can explain the choice may be learning more than a child who never spends because every decision requires permission.
Common confusion about control and independence
A common misunderstanding is assuming that giving a child the card means giving the child complete financial independence. That is not how I would approach Greenlight. The parent-managed structure is most useful precisely because independence is introduced in stages. The child practices making choices, while the adult remains close enough to guide the process.
Another confusion is treating the app as an automatic teacher. It can make spending activity easier to discuss, but it cannot replace a family’s decisions about allowances, acceptable purchases or saving priorities. If the parent never reviews the activity or explains the boundaries, the child may experience only the card and miss the educational part.
Some families may also wonder whether the app is suitable for several children. It can be considered by larger households, but the practical question is whether the adults can keep each child’s expectations clear and give each child enough attention. A system that works beautifully for one child may feel administrative when every transaction becomes part of a crowded family routine.
When a traditional alternative may be better
If your main goal is teaching physical budgeting, envelopes or cash may be more direct. Cash makes the remaining amount visible without requiring a phone, and some younger children understand that limit immediately. In that situation, Greenlight may add technology without solving the teaching problem you actually have.
If your teenager is ready for broader banking responsibilities, a conventional youth banking arrangement may offer a better next step, depending on what your family needs. Greenlight’s appeal is the supervised bridge between dependence and independence. It is not automatically the best permanent financial home for every older teen.
On the other hand, a normal debit card can be too blunt for a child who is still learning. The parent-managed design gives Greenlight a clearer role than a basic card: it creates a framework for explaining choices. I would choose it when that framework is the priority, not merely because the child wants a card.
Privacy, trust and the parent-child balance
Parents should think about how they will use visibility responsibly. Knowing where a child spends money can support safety and teaching, but checking every small purchase without discussion may undermine trust. I would explain what will be reviewed and why, then give the child room to make ordinary decisions within those boundaries.
For teenagers especially, the tone matters. The app should not become a way to turn every purchase into an argument. A useful compromise is to reserve detailed conversations for unusual, unplanned or important spending while letting ordinary agreed purchases pass without unnecessary drama.
How I would use it after the first week
After the initial setup and first successful purchase, I would look for one clear improvement rather than adding many rules. Perhaps the child checks the balance before shopping, tells the parent about an unexpected issue or waits before making an impulse purchase. That single behavior is a better sign of progress than a complicated family budget that nobody follows.
Then I would revisit the arrangement after several check-ins. Is the child asking better questions? Is the parent spending less time correcting misunderstandings? Are the agreed uses of the card still realistic? If the answer is no, simplify the routine before adding more oversight. The app should support the family’s habits, not create a second job for the adults.
My recommendation for first-time families
Greenlight: For Families is a strong option for parents who want a controlled introduction to card spending and are prepared to participate. I like that its central idea is practical: a child can practice everyday decisions while an adult remains involved through the app. That makes the first meaningful success achievable—a planned purchase, a calm review and a clearer understanding of what happened.
I would skip it if you want an entirely independent debit card, dislike managing a family finance routine or already have a simpler method that your child understands. The free download also should not be confused with a promise that every family will find the overall arrangement effortless; the real commitment is the time and attention needed to make parent management useful.
For the right household, though, the app can turn ordinary spending into repeatable learning. Install it on a compatible device, decide what you want the child to practice, begin with one small agreed purchase and review that experience together. The first win is not simply completing a transaction; it is helping the child understand the choice behind it.
That is why I would recommend Greenlight: For Families to a parent looking for a middle ground between cash and unrestricted banking. It is most effective when treated as a shared family tool rather than a magic solution. Used with clear expectations and a light weekly routine, it offers a reassuring path from adult supervision toward real-world money confidence.
Pros
- Parents can manage cards, spending limits, and permissions from one dashboard.
- Kids receive instant spending notifications, helping families discuss money habits.
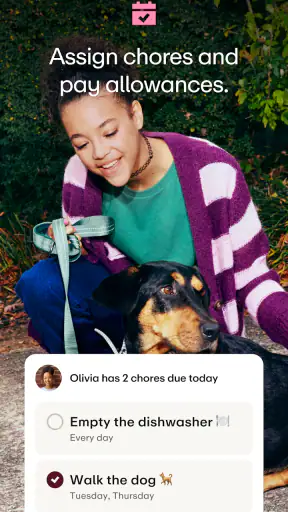
- The app supports chore payments and allowance management in one place.
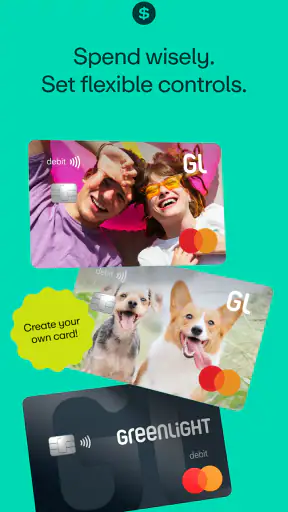
- Customizable card controls can reduce the risk of unauthorized purchases.
- Family-focused design makes basic budgeting easier for younger users.
Cons
- Some features may require a paid Greenlight subscription.
- The app is mainly useful for families using Greenlight cards.
- Parental approval can delay purchases when immediate payment is needed.
- Availability of features may vary by plan, location, or account type.
- Children’s access and spending depend heavily on parental settings.
FAQs for Greenlight: For Families
What is Greenlight: For Families?
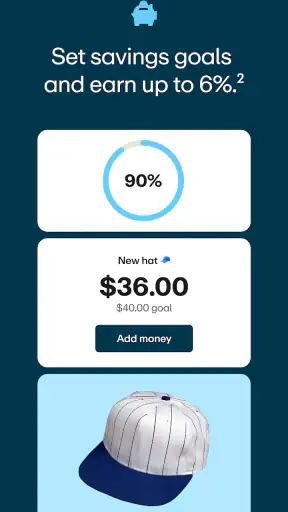
Greenlight: For Families is a family-focused financial app designed to help parents manage money for their children while teaching practical money skills. Parents can typically use it to provide a supervised spending card, assign chores, set goals, monitor transactions, and discuss saving habits. The exact features and availability may depend on the selected Greenlight plan and the user’s location.
How does the Greenlight card for children work?
The Greenlight card is generally connected to a parent-managed account, allowing children to spend money within limits set by their parents. Parents can add funds, view purchases, receive transaction notifications, and sometimes control where the card can be used. It is not an unrestricted bank account, so families should review spending controls, merchant limitations, and applicable terms before using it.
Is Greenlight: For Families safe for children to use?
The app is built around parental supervision, which can make it safer for children than using an ordinary payment card without controls. Parents can monitor activity and establish spending rules, while children gain experience making purchases. However, no financial app eliminates all risks. Parents should enable available security features, discuss scams and privacy, and regularly review account activity with their child.
Does Greenlight: For Families charge a monthly fee?
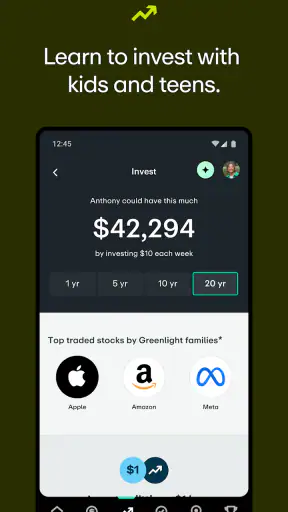
Greenlight: For Families may require a paid subscription, and pricing can vary according to the plan, promotions, billing period, and region. Some plans may include additional features such as investing tools, identity protection, or enhanced family controls. Before downloading or starting a trial, check the current price, included services, renewal terms, and whether any optional features create extra costs.
What age is Greenlight: For Families suitable for, and what does a parent need to sign up?
Greenlight is primarily intended for families with children and teenagers, although the most suitable age depends on the child’s maturity and the features the family wants to use. A parent or legal guardian normally creates and controls the account. Registration may require personal information, identity verification, a funding source, and agreement to financial-service terms. Eligibility requirements can vary by location.

Greenlight: For Families
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@greenlight.com, visit https://www.greenlight.com/, or review their https://greenlight.com/privacy/.










